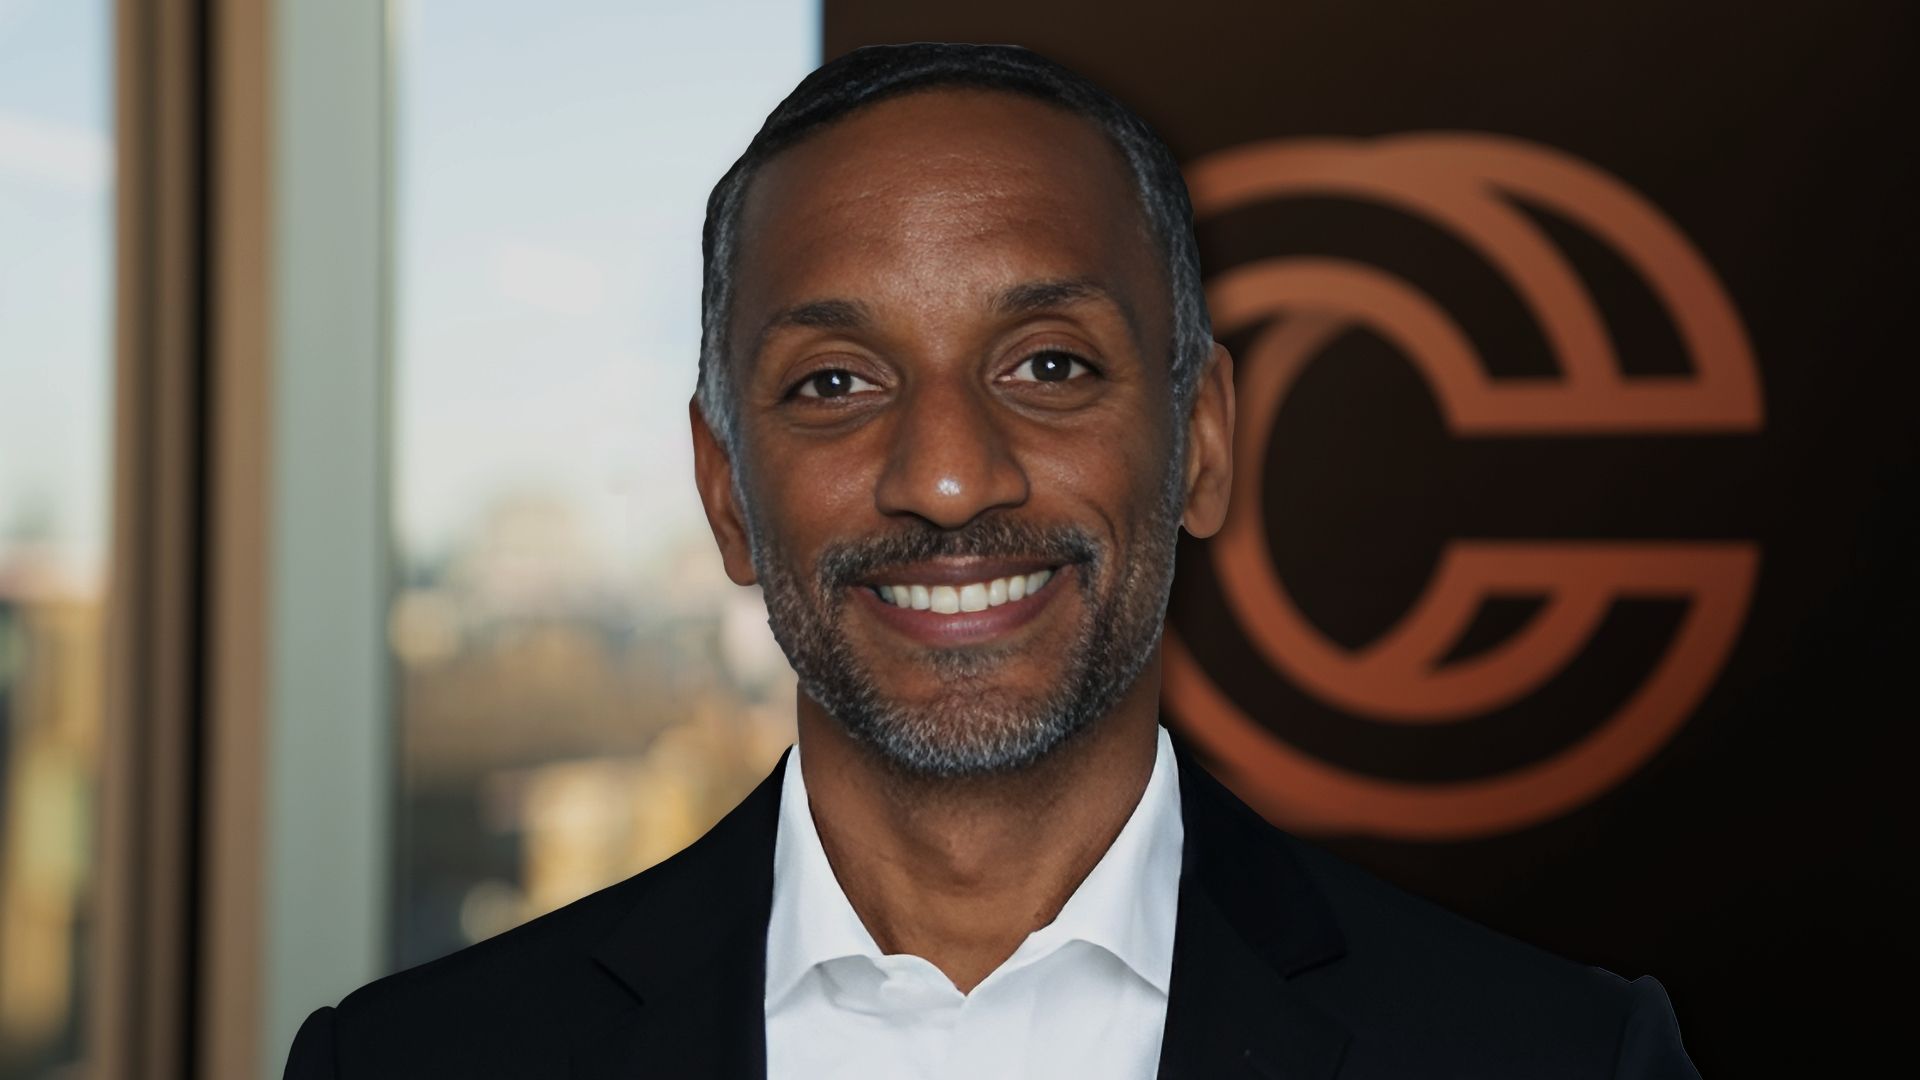
# Copper CEO Exits as Custody Firm Hunts for Buyer
Amar Kuchinad has departed from Copper, the cryptocurrency custody platform, marking a leadership vacuum at a critical moment for the company. Kuchinad served as CEO since 2024, and his exit occurs as Copper enters its fourth month of searching for a buyer.
The departure signals internal turbulence at a time when institutional crypto custody remains a competitive and consolidating market. Custody firms act as critical infrastructure, holding digital assets on behalf of exchanges, hedge funds, and institutional investors. Control of customer funds and regulatory compliance demands make leadership stability paramount in this sector.
Copper's sale process began months ago, suggesting the company faced pressure to find strategic partners or new ownership. The extended timeline of four months indicates negotiations have not closed quickly, potentially pointing to valuation disputes, due diligence complications, or a limited pool of qualified buyers willing to acquire an independent custody player.
The cryptocurrency custody space has experienced significant consolidation. Established players like Coinbase Custody, Kraken Custody, and Fidelity Digital Assets command substantial market share. Newer entrants and independent operators like Copper compete for institutional clients by offering specialized custody solutions, often with enhanced security features or regulatory positioning for specific jurisdictions.
Kuchinad's sudden departure creates uncertainty about Copper's strategic direction. The CEO role involves relationship management with institutional clients, regulatory negotiations, and fundraising conversations with potential acquirers. His exit mid-sale process may complicate negotiations or signal internal disagreement about deal terms or company valuation.
Copper raised capital previously at a significant valuation, reflecting investor confidence in crypto custody infrastructure before market downturns in 2022 and 2023. A forced sale after such investments typically means shareholders accept reduced valuations, a painful but common outcome for companies unable to reach profitability or sustain growth independently.
The firm operates in multiple jurisdictions, holding actual cryptocurrency and fiat on behalf of clients. This regulatory complexity adds layers to any potential acquisition. Buyers must inherit existing compliance obligations, audit requirements, and custody licenses across different regions. These barriers can limit the acquirer pool to large financial institutions or well-capitalized crypto platforms already operating custody services.
Custody market dynamics have shifted post-FTX collapse. Institutional investors increased scrutiny on fund security and operator solvency. Some clients migrated to larger, more established custody providers deemed safer. This exodus may have accelerated Copper's need to seek buyers rather than continue as an independent operator.
The broader crypto infrastructure sector faces a bifurcation. Well-capitalized platforms like Kraken and Coinbase absorb custody functions, using them as stickier customer retention tools. Standalone custody firms face pressure to either consolidate, specialize in niche services, or exit. Copper's sale process fits this pattern.
Kuchinad's replacement and the timeline for announcing a deal will shape Copper's near-term credibility with clients. Long customer retention during transitions requires confident messaging and continuity in service delivery. Extended leadership vacancies in custody firms create client anxiety and potential account migrations.
The exit highlights how even well-funded crypto infrastructure plays struggle in a market dominated by consolidating giants. Institutional custody remains essential infrastructure, but independent operators increasingly find themselves acquired or folded into larger platforms rather than thriving as standalone businesses.