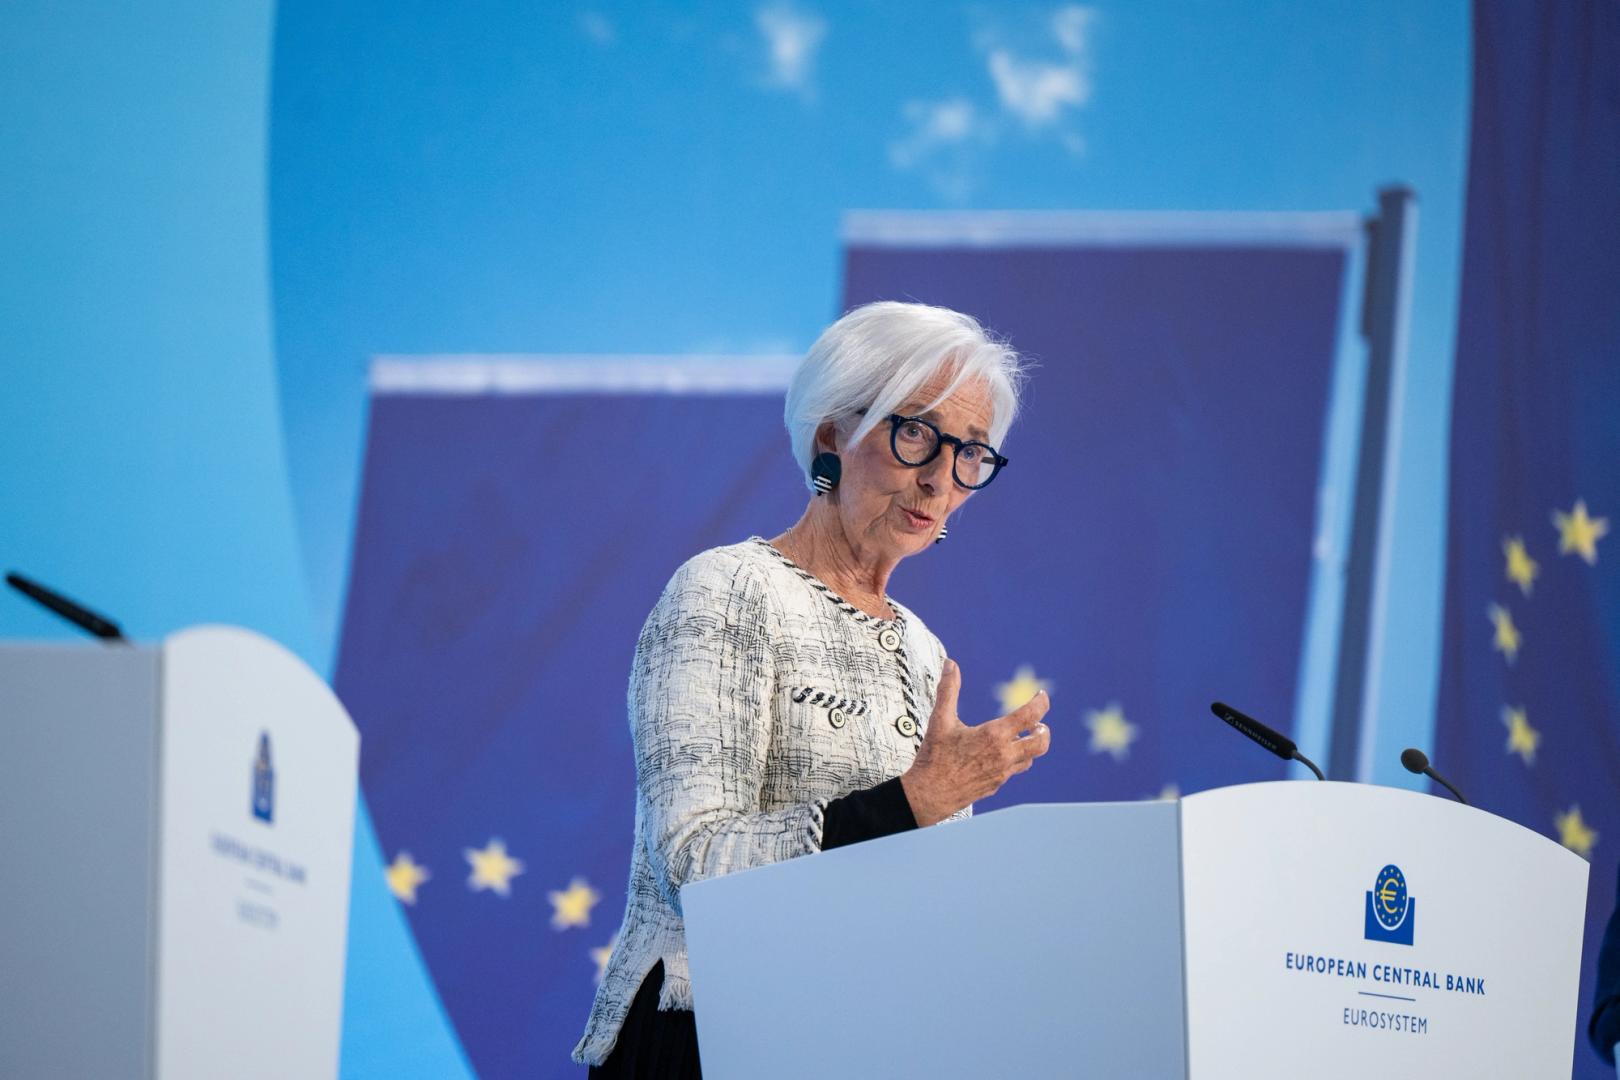
The European Central Bank has launched an active recruitment drive for merchants to participate in a year-long pilot program testing its digital euro, a central bank digital currency (CBDC) that aims to modernize payments across the eurozone.
The pilot runs for 12 months and covers four distinct payment channels: online transactions, mobile payments, in-store purchases, and peer-to-peer transfers. This breadth of testing scenarios reflects the ECB's pragmatic approach to CBDC design. Rather than launching a finished product, officials want real-world feedback on how merchants and consumers interact with the digital currency across different spending contexts.
The ECB has been signaling serious intent on its digital euro project for years, but this merchant recruitment phase marks a tangible shift from theoretical planning to operational testing. The central bank needs merchant participation to validate technical infrastructure, settlement mechanisms, and user experience design. Without retailers willing to accept the digital euro in their payment systems, the pilot lacks the market authenticity needed to generate actionable data.
The peer-to-peer component deserves specific attention. CBDCs designed for direct consumer-to-consumer transfers without intermediaries address a genuine use case, particularly for unbanked and underbanked populations. The eurozone includes several member states with significant cash-dependent demographics, and a digital euro accessible via mobile phones could improve financial inclusion while reducing reliance on physical currency infrastructure.
This initiative arrives amid broader European regulatory momentum. The Markets in Crypto Assets Regulation (MiCA) established clear rules for crypto service providers across the EU last year, creating a more structured environment for digital asset experimentation. The ECB's CBDC work sits at the intersection of this regulatory framework and central banking policy.
Merchant participation carries practical complexity. Retailers must integrate the digital euro into existing point-of-sale systems, connect to settlement infrastructure, and train staff on new payment flows. The ECB likely expects technical integration challenges during testing. How quickly merchants can onboard, and whether the integration proves seamless or cumbersome, will directly influence commercial viability once a full launch occurs.
The timing also reflects geopolitical context. Central banks worldwide, from China to Sweden to Singapore, are testing CBDCs with increasing urgency. The Federal Reserve has been more cautious, but the ECB's commitment to a operational pilot demonstrates Europe's determination to maintain monetary system relevance in a digital-first economy. The digital euro positions the eurozone competitively against potential alternative payment systems and provides the ECB direct visibility into digital payment flows.
Merchant feedback during this phase will shape critical policy decisions. The ECB needs to understand settlement speed requirements, fraud prevention needs, offline functionality demands, and cross-border payment considerations. A 12-month window provides reasonable time to stress-test these dimensions without premature scaling.
The pilot's success depends partly on merchant recruitment depth. Early adopters in major economies like Germany, France, and Italy will carry outsized influence on pilot outcomes. If large retailers participate, the test generates meaningful transaction volume and diverse use cases. If recruitment stalls with only niche participants, the pilot data becomes less representative.
The digital euro remains years away from public circulation, but this merchant testing phase moves from conceptual development into implementation validation. How merchants respond will determine whether the ECB's CBDC becomes a functional alternative to commercial bank digital currencies or remains a regulatory compliance exercise.