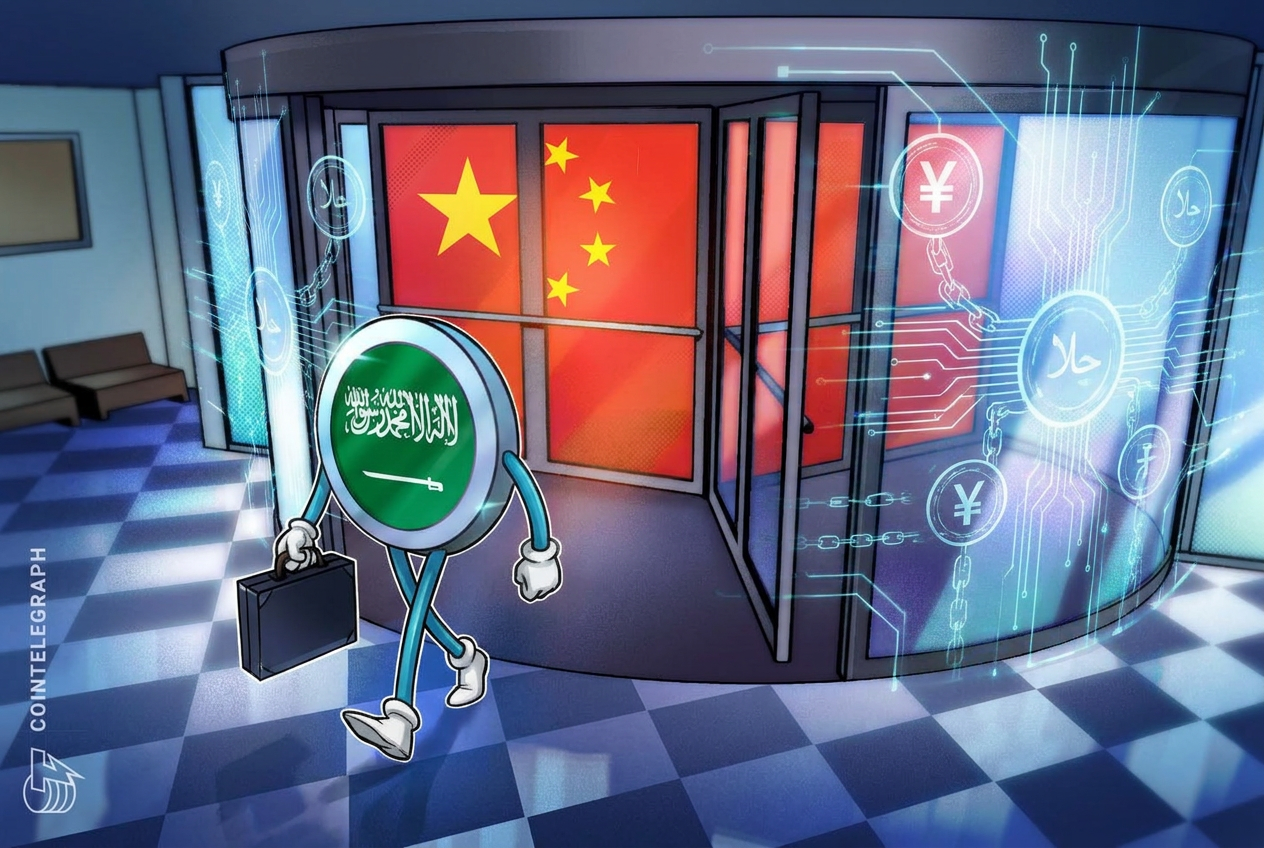
Saudi Arabia's withdrawal from mBridge marks a significant fracture in the China-led central bank digital currency coalition. The Financial Times reported the kingdom exited the cross-border CBDC platform, a move that reflects mounting geopolitical pressure from Washington and shifts in Riyadh's strategic positioning.
mBridge emerged as one of the most ambitious CBDC initiatives beyond US control. The platform connected the central banks of China, Saudi Arabia, the United Arab Emirates, Hong Kong, and Thailand in a network designed to facilitate direct currency settlement without relying on SWIFT or dollar intermediaries. The project represented a direct challenge to US financial hegemony, offering participating nations an alternative payment infrastructure insulated from American sanctions and oversight.
Saudi Arabia's exit carries outsized symbolic weight. As the world's largest crude oil exporter and a regional economic anchor, the kingdom's participation lent legitimacy to mBridge and signaled non-Western emerging markets could coordinate outside dollar-denominated systems. Riyadh's departure suggests the US successfully leveraged its leverage over the Saudis. Washington maintains substantial military relationships with the kingdom and retains significant influence over petroleum pricing mechanisms and regional security arrangements.
The timing coincides with intensifying American pressure on de-dollarization efforts. US policymakers have publicly flagged mBridge as a threat to dollar dominance and financial stability. Congressional committees have scrutinized CBDCs and alternative payment rails as potential tools for sanctions evasion and reducing American financial coercion capacity. Saudi Arabia likely faced explicit pressure to choose between participating in US-aligned financial systems or maintaining the benefits of its relationship with Washington.
mBridge continues operating with remaining members, though Saudi withdrawal weakens the coalition's geographic reach and economic heft. The platform still connects China, the UAE, Hong Kong, and Thailand. Without the Saudi pivot and its oil-based economy, mBridge loses a critical economic anchor and becomes more explicitly characterized as a China-centric initiative rather than a broader emerging market consensus.
The Saudi decision also reflects pragmatic calculation. The kingdom maintains deep energy relationships with both the US and China but derives greater strategic value from American security guarantees in an unstable Middle East. Participation in Chinese payment infrastructure offered theoretical long-term benefits but created immediate friction with Washington. The kingdom opted for stability with its established ally over experimental alternative systems.
This development matters beyond bilateral US-Saudi relations. Other potential mBridge members face identical pressure calculations. India, Brazil, and other nations considering participation now observe that membership carries real diplomatic and economic costs. The Saudi exit signals that Washington actively punishes defections from dollar-based systems and that the benefits of joining China-led initiatives may not justify the downside.
mBridge remains operational and technically functional, but it becomes harder to present as a genuine multilateral effort. The platform increasingly resembles a Chinese-dominated regional payment system rather than a true alternative to Western financial architecture. Without major emerging market economies like Saudi Arabia, mBridge struggles to offer the critical mass necessary to challenge dollar settlement.
The broader CBDC landscape remains contested. Central banks worldwide continue developing digital currencies, but cross-border CBDC platforms designed specifically to circumvent dollar dominance face structural headwinds. Saudi Arabia's departure reflects these realities.